



Black Book: Weekly Market Update
The general mood from those we’ve talked to continues to be that we will have a few more months of strength, but what we have been observing in a variety of auctions leads us to believe that this may not be the case.

Wholesale Prices, Week Ending April 29
The market continued to increase last week, but as has been the trend for the last few weeks, the rate of gains is slowing. We are now seeing more signs of softening in the market, with seven of the 22 segments we track reporting declines, the highest number of segments reporting declines since mid-February.
This Week Last Week 2017-2019 Average (Same Week)
Car segments +0.27% +0.37% -0.05%
Truck & SUV segments +0.17% +0.22% +0.04%
Market +0.20% +0.27% +0.00%
Car Segments
On a volume-weighted basis, the overall car segment increased +0.27%. For reference, the previous week, cars increased by +0.37%.
Six of the nine car segments increased last week.
Sporty car reported the largest increase last week, up +0.81%. This marks the 15th consecutive week of increases for the segment, with an average weekly gain of +0.64%.
Prestige luxury (-0.16%), near luxury (-0.08%), and premium sporty (-0.06%) car segments all reported declines.
Truck / SUV Segments
The volume-weighted, overall truck segment increased +0.17%, compared with the prior week’s increase of +0.22%.
Nine of the 13 truck segments reported increases last week.
Minivan (+0.47%), small pickup (+0.43%), and full-size pickup (+0.39%) had the largest truck segment gains.
The compact luxury crossovers (-0.03%) declined for a second consecutive week, and subcompact crossovers (-0.06%) declined for the first time since early February.
Weekly Wholesale Index
The graphic below looks at trends in wholesale prices of 2- to 6-year-old vehicles, indexed to the first week of the year. The index is computed keeping the average age of the mix constant to identify market movements.
Calendar years 2020 and 2021 ended with used wholesale prices at elevated levels. With economic patterns, including the automotive market, driven by the pandemic, normal seasonal patterns in the wholesale market, e.g., the 2019 calendar year, were not observed for most of the last three years. We saw a similar picture in 2009, at the end of the Great Recession. Calendar year 2021 did not have typical seasonality patterns, as the market had rapid increases in wholesale values for most of the year. The Wholesale Weekly Price Index reached the highest point of the year at the end of December 2021, reporting over 1.51 points. In 2022, the price index was on a mild rollercoaster until July, after which point, prices were on a continuous decline until the end of the year.
Retail (Used and New) Insights
Chevrolet announced plans to discontinue production of the Chevrolet Bolt at the end of the year, and then the Michigan facility will receive a renovation to prepare for production of the all-electric versions of the Silverado and Sierra pickups.
Dealers Auto Auction, the U.S.’ fourth-largest auction group, is expanding with the purchase of OKI Cincinnati Auto Auction. The auction will be renamed to DAA Cincinnati and marks the 11th auction location for the group.
Stellantis, in a move to cut costs in its push toward electrification, is offering voluntary buyouts to more than 30,000 hourly and salaried nonunion U.S. employees. This is after General Motors did the same thing, with roughly 5,000 employees opting into the buyout program.
Used Retail Prices
Used retail prices are more accessible than in years past due to the proliferation of "no-haggle pricing" for used-vehicle retailing. Transparent pricing upfront makes the car-buying process more enjoyable for customers and allows Black Book to accurately measure retail market trends.
At the onset of the pandemic, in CY2020, used retail prices increased slightly, following typical seasonal patterns, and then began dropping in April, finally hitting a low point in the late spring months. By late summer of CY2020, used retail prices increased as supply of new-vehicle inventory started to become scarce, but retail demand slowed at the end of CY2020, resulting in declining retail asking prices for the last several weeks of the year. When CY2021 kicked off, demand rebounded while retail prices lagged slightly behind wholesale prices; March 2021 started the dramatic increases in used retail prices, fueled by stimulus payments, tax season, and shortages of new inventory. During the third quarter, retail prices continued to rise at a slower rate but soon picked up once again to start the fourth quarter, when prices steadily increased week after week. As CY2021 came to an end, the retail listing price index closed 36% above where the year began. The index then remained relatively stagnant through most of CY2022. In the fourth quarter of 2022, the Retail Listings Price Index declines started but were not as steep as the wholesale price index.
This analysis is based on approximately two million vehicles listed for sale on U.S. dealer lots. The graphic below looks at 2- to 6-year-old vehicles. The index is computed keeping the average age of the mix constant to identify market movements.
Inventory
Used Retail
The Used Retail Active Listing Volume Index reverted back to one at the start of 2023. Currently, the index sits at 0.95 points.
The used retail days-to-turn estimate is currently around 53.
Wholesale
Auction conversion rates remained stable for the second week in a row, and with prices showing a few more negative movements, it is leaving us wondering if they will continue in that direction. The general mood from those we’ve talked to continues to be that we will have a few more months of strength, but what we have been observing in a variety of auctions leads us to believe that this may not be the case. In addition to softening in some values at the auction, we are also seeing a drop in inventory at open and closed OEM sales. As always, the Black Book team will continue to monitor and report on these developing trends.
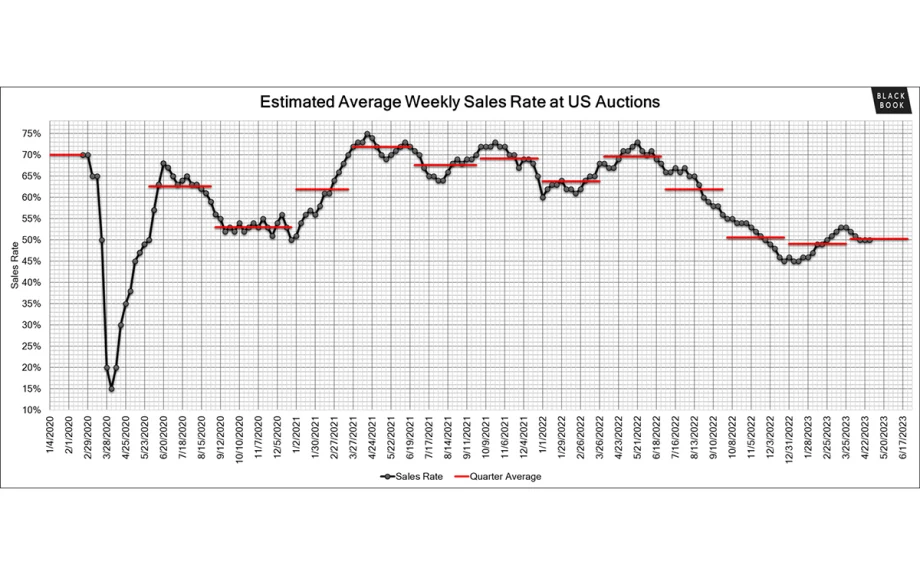
The Estimated Average Weekly Sales Rate remained at 50% last week.
Originally posted on Auto Dealer Today
More Industry

Penske Auto Group Deal a Record
The deal to take the dealership and transportation services company private sets a new pace for industry buy-sell transactions.
Read More →
War Toll a Damper on Used Auto Prices
Cox Automotive found wholesale depreciation to be elevated in September amid high fuel prices and this year's unusual hurricane season.
Read More →
Bridge the Maintenance Gap
With many drivers missing recommended maintenance, service departments offering transparency and efficiency have a better chance of reaching financially strained consumers.
Read More →
California Store Has New Owner
The longtime dealership in the northern part of the state is known for robust fleet sales and has served the state capital for 115 years.
Read More →
BMW Plant Pursues Cleaner Energy
BMW Group Plant Leipzig has utilized hydrogen to help power its production since 2013, but a new pipeline is planned to take it to another level.
Read More →
Auto Affordability Inches Up
The latest Cox Automotive and Moody’s Analytics index shows a slight increase in new-vehicle affordability despite high prices.
Read More →
Ohio Auto Group Under New Ownership
After 79 years with the Schluter family, Mansfield Auto Group has been acquired by Missouri-based Clement Auto Group.
Read More →
RV Group Expands Carolina Footprint
Blue Compass RV Columbia Northeast is the 13th RV dealership owned by Blue Compass in the Carolinas.
Read More →
Agent Acumen
An Agent Summit panel of people who’ve been supporting auto dealers for years gave both timely and timeless advice for those starting out or mulling the prospect.
Read More →
Missed Maintenance Creates Opportunity
As families get back on the road and into daily school routines, service drives have an opportunity to capture customers who are behind on recommended vehicle maintenance.
Read More →