



Ukraine War Challenges EV Supply Chains
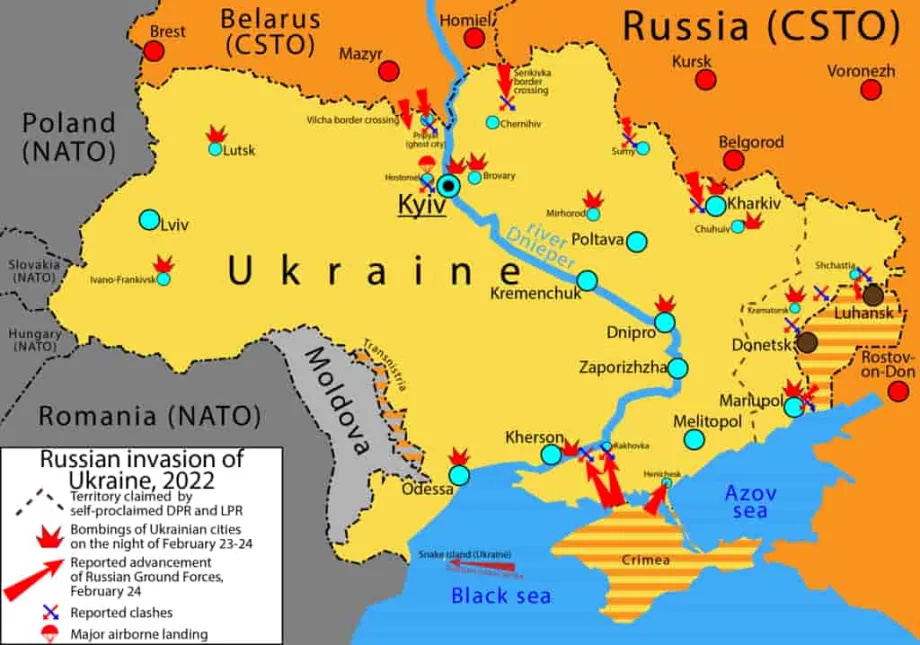
Supply chain challenges rising from the war in Ukraine could make electric vehicles (EV) more expensive to build as raw material prices shoot up.

cleverlysmart.com
Supply chain challenges rising from the war in Ukraine could make electric vehicles (EV) more expensive to build as raw material prices shoot up.
Higher prices could challenge consumer EV adoption as automakers move to roll out new battery-powered models, warns S&P Global Mobility.
The challenges may affect batteries used in several popular EV models. The batteries use nickel and Russia is a top supplier of nickel used in automotive batteries. The conflict has caused volatility in nickel pricing, with prices surging up to $100,000 per ton on March 8. This figure is up from around $30,000 a day earlier.
S&P Global Mobility predicts the Tesla Model Y crossover could see battery costs rise up to $8,000 per vehicle. The Mercedez-Benz EQS, S&P predicts, will see higher hits as raw materials skyrocket up to $11,000 compared to 2021 prices.
S&P Global Mobility, formerly IHS Markit's automotive team, reports Russia's invasion of Ukraine has exacerbated price pressures by inflating raw material prices. Russia is the world's third-largest supplier of the metal, making nickel one of the hardest hit commodities.
Norilsk is one of Russia’s largest nickel suppliers. German chemicals giant BASF, which manufactures nickel and cobalt for automotive batteries, said it will not sign new agreements with Norilsk because of the invasion. Other manufacturers have announced they will do the same.
Nickel has traded for between $10,000 and $20,000 per ton over the past decade. But traded for over $100,000 on March 8. This trigged a weeklong suspension of trading on the London Metal Exchange. Prices have fallen since that date.
"It's clear that at current prices, we will see, at a minimum, any price reduction linked to batteries' economies of scale wiped out by increased input costs," the S&P March 9 report reads.
"It is also clear that should these elevated price levels continue into 2023 and beyond, the likelihood of a delay of the tipping point for [internal combustion engine] versus BEV cost parity — a critical metric to measure battery-electric vehicle adoption — markedly increases,” it continues.
According to S&P, battery manufacturers substitute nickel for cobalt, which has been linked to human rights abuses in Congo.
The auto industry faces other problems because of the war:
Mercedes reports its $2.2 billion in assets in Russia are at risk if the country decides to expropriate the property of foreign companies that have exited Russia over the invasion. Russian lawmakers have proposed taking temporary control of departing companies where foreign ownership exceeds 25%.
Stellantis plans to move some van production from Russia to western Europe and noted plans to freeze investment plans in Russia. Its Russian plant, owned with Mitsubishi in Kaluga, makes Peugeot, Opel and Citroen-brand vans.
Volkswagen CEO Herbert Diess announced the company will shift more vehicle production to China and North America over the conflict. U.S. Volkswagen dealers expect more crossover inventory in the coming months. Diess predicts there will be volatility in commodities markets until 2026.
Michelin, which has made tires in Russia since 2004, plans to suspend industrial activity in the country and will halt exports to it.
Audi shut down a German plant that builds the A4, A5, A6 and A7 models because of supply shortages stemming from the war and the semiconductor shortage.
BMW foresees lower profit margins for its automotive business in 2022 because of the war, forecasting earnings before interest and taxation of 7% to 9%, down from over 10% in 2021. BMW will resume full output this week at its factories in Germany and the U.K. that were down due to parts shortages because of the conflict.
S&P also has lowered its global vehicle production forecast by 2.6 million units each for 2022 and 2023 because of the combined impact of the Ukraine invasion and the semiconductor chip shortage. It forecasts that automakers will produce 81.6 million vehicles in 2022 and 88.5 million in 2023.
Originally posted on Auto Dealer Today
More Industry

Penske Auto Group Deal a Record
The deal to take the dealership and transportation services company private sets a new pace for industry buy-sell transactions.
Read More →
War Toll a Damper on Used Auto Prices
Cox Automotive found wholesale depreciation to be elevated in September amid high fuel prices and this year's unusual hurricane season.
Read More →
Bridge the Maintenance Gap
With many drivers missing recommended maintenance, service departments offering transparency and efficiency have a better chance of reaching financially strained consumers.
Read More →
California Store Has New Owner
The longtime dealership in the northern part of the state is known for robust fleet sales and has served the state capital for 115 years.
Read More →
BMW Plant Pursues Cleaner Energy
BMW Group Plant Leipzig has utilized hydrogen to help power its production since 2013, but a new pipeline is planned to take it to another level.
Read More →
Auto Affordability Inches Up
The latest Cox Automotive and Moody’s Analytics index shows a slight increase in new-vehicle affordability despite high prices.
Read More →
Ohio Auto Group Under New Ownership
After 79 years with the Schluter family, Mansfield Auto Group has been acquired by Missouri-based Clement Auto Group.
Read More →
RV Group Expands Carolina Footprint
Blue Compass RV Columbia Northeast is the 13th RV dealership owned by Blue Compass in the Carolinas.
Read More →
Agent Acumen
An Agent Summit panel of people who’ve been supporting auto dealers for years gave both timely and timeless advice for those starting out or mulling the prospect.
Read More →
Missed Maintenance Creates Opportunity
As families get back on the road and into daily school routines, service drives have an opportunity to capture customers who are behind on recommended vehicle maintenance.
Read More →