

CFPB Issues Proposal to End Forced Arbitration
ALBUQUERQUE, N.M. — As expected, the Consumer Financial Protection Bureau used its 34th field hearing to issue its proposed rule prohibiting mandatory arbitration clauses in finance contracts. Companies will still be able to include such clauses in their contracts under the bureau’s proposal; they just won’t be able to use such agreements to stop consumers ... Read More »

ALBUQUERQUE, N.M. — As expected, the Consumer Financial Protection Bureau used its 34th field hearing to issue its proposed rule prohibiting mandatory arbitration clauses in finance contracts. Companies will still be able to include such clauses in their contracts under the bureau’s proposal; they just won’t be able to use such agreements to stop consumers from being part of a class action in court.
Issued on May 5, the proposal comes more than a year after the bureau issued its 728-page report on the use of pre-dispute arbitration clauses in consumer finance markets. The study, which reviewed more than 1,800 consumer finance arbitration disputes filed over a three-year period beginning in 2010 and more than 3,400 individual federal lawsuits, found that consumers were awarded less than $175,000 in damages and less than $190,000 in debt forbearance in arbitration suits vs. just less than $1 million in federal lawsuits.
“Today, we are proposing a new regulation for public comment and further consideration. If finalized in its current form, the proposal would ban consumer financial companies from using mandatory pre-dispute arbitration clauses to deny their consumers the right to band together to seek justice and meaningful relief from wrongdoing,” said CFPB Director Richard Cordray at the hearing, held at the Albuquerque Convention Center. “This practice has evolved to the point where it effectively functions as a kind of legal lockout. Companies simply insert these clauses into their contracts for consumer financial products or services and literally, with the stroke of a pen, are able to block any group of consumer from filing joint lawsuits known as class actions.”
Through the Dodd-Frank Wall Street Reform and Consumer Protection Act, Congress asked the CFPB to study the use of mandatory arbitration clauses in consumer financial markets. Congress also gave the bureau the power to issue regulations that are “in the public interest, for the protection of consumers, and consistent with the study.”
Released in March 2015, the CFPB’s study concluded that very few consumers bring individual actions against their financial service provider, either in court or in arbitration. It also showed that at least 160 million class members were eligible for relief over the five-year period studied. Those settlements totaled $2.7 billion in cash, in-kind relief, and attorney’s fees and expenses. In its press release announcing the proposed rule, the bureau said the study’s findings do not account for the “the potential value to consumers of class action settlements requiring companies to change their behavior.”
But not all findings in the study supported the elimination of mandatory arbitration clauses. For instance, the study showed that in many class action cases where the principal purpose of seeking class relief was to pressure a settlement, members of the class action got nothing or next to nothing. It also found that class action cases almost never make it to trial, while a significant percentage of arbitration proceedings actually resolve the disputes. The study also showed that arbitration is both faster and more economical than litigation.
“Late last year, the CFPB released a study on arbitration, which the bureau says shows that consumers are harmed by arbitration agreements as opposed to class action lawsuits. However, a careful review of the CFPB’s study demonstrates that the opposite is true …,” the American Financial Services Association wrote in a news brief issued last Thursday. “In 60% of class actions studied by the CFPB, consumers received no remuneration at all.
“In the 15% of cases where consumers received monetary compensation in class actions, they received an average of just $32.25, after waiting an average of 23 months,” the associated added. “In contrast, consumers who prevailed in arbitration agreements, on average, received $5,389. The real winners in class action lawsuits are plaintiff’s attorneys, who divided approximately $424 million in fees.”
The CFPB said its proposal, which will be open for public comment for the next three months, would open up the legal system to consumers so they can file or join a class action someone else files. And while companies will still be able to include arbitration clauses in their contracts under the proposal, the clauses would have to say explicitly that they cannot be used to stop consumers from being part of a class action in court. The proposal would also provide the specific language companies must use.
Additionally, the bureau’s proposal would require companies with arbitration clauses to submit to the CFPB claims, awards, and certain related materials that are filed in arbitration cases. This would allow the bureau to monitor consumer finance arbitrations to ensure that the arbitration process is fair for consumers. The bureau is also considering publishing information it would collect in some form so the public can monitor the arbitration process as well.
“If arbitration truly offers the benefits that its proponents claim, such as providing a less costly and more efficient means of dispute resolution, then it stands to reason that companies will continue to make it available,” Cordray said at the bureau’s hearing. “So the essence of the proposal issued today is that it would prevent mandatory arbitration clauses from imposing legal lockouts to deny groups of consumers the right to pursue justice and secure meaningful relief from wrongdoing.”
That’s not how the AFSA views the bureau’s proposal. “Despite a wealth of evidence suggesting that the bureau’s interpretation of its own study is flawed, today’s rule, in its present form, would have a negative impact on customers by taking away a valuable tool to resolve disputes,” the associated stated. “AFSA will comment on the proposed rule and will continuing its ongoing dialogue with the CFPB.”
More Industry
War Toll a Damper on Used Auto Prices
Cox Automotive found wholesale depreciation to be elevated in September amid high fuel prices and this year's unusual hurricane season.
Read More →
Bridge the Maintenance Gap
With many drivers missing recommended maintenance, service departments offering transparency and efficiency have a better chance of reaching financially strained consumers.
Read More →
California Store Has New Owner
The longtime dealership in the northern part of the state is known for robust fleet sales and has served the state capital for 115 years.
Read More →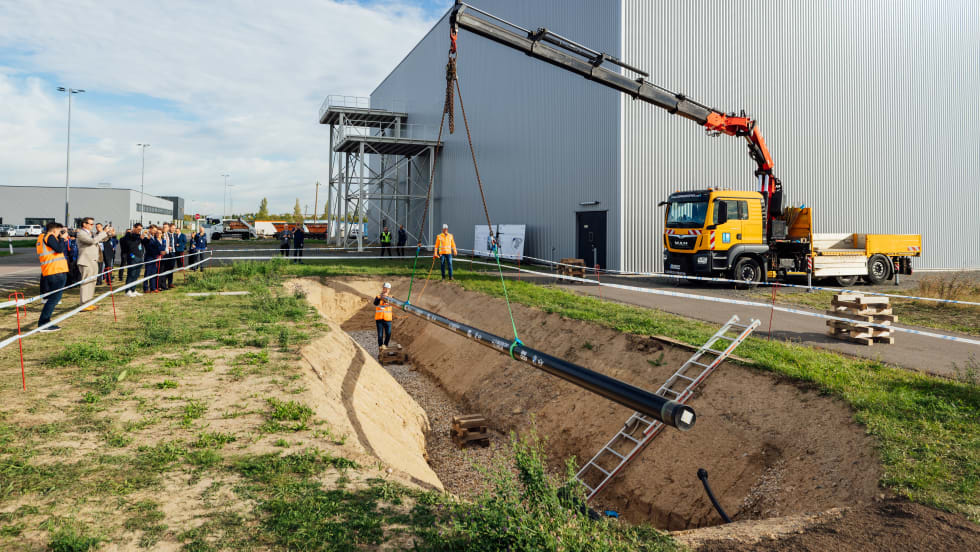
BMW Plant Pursues Cleaner Energy
BMW Group Plant Leipzig has utilized hydrogen to help power its production since 2013, but a new pipeline is planned to take it to another level.
Read More →
Auto Affordability Inches Up
The latest Cox Automotive and Moody’s Analytics index shows a slight increase in new-vehicle affordability despite high prices.
Read More →
Ohio Auto Group Under New Ownership
After 79 years with the Schluter family, Mansfield Auto Group has been acquired by Missouri-based Clement Auto Group.
Read More →
RV Group Expands Carolina Footprint
Blue Compass RV Columbia Northeast is the 13th RV dealership owned by Blue Compass in the Carolinas.
Read More →
Agent Acumen
An Agent Summit panel of people who’ve been supporting auto dealers for years gave both timely and timeless advice for those starting out or mulling the prospect.
Read More →
Missed Maintenance Creates Opportunity
As families get back on the road and into daily school routines, service drives have an opportunity to capture customers who are behind on recommended vehicle maintenance.
Read More →
Mitsubishi Unveils U.S. Plan
The automaker announced a strategy that includes an expanded lineup and dealership presence, along with more ‘rugged’ and electric models.
Read More →