

Unwanted Answers to Compliance Questions
Some practices are better left undone at the dealership, for its, and the consumer's, good.

Digitizing sales and F&I processes and updating policies are two ways dealers can build in compliance.
Pexels/Markus Winkler
My job is to help dealerships find compliant solutions for the processes they’ve implemented. I am asked compliance questions daily by dealership owners and managers, and I would say I am able to usually provide a compliance solution that the owner or manager finds agreeable.
I said usually. Occasionally the answer to a question is not what the person wants to hear.
When I started gvo3 & Associates over 22 years ago the burning question was, “How can I add the subprime acquisition fee to the vehicle sales price?” The short answer is you can’t. The long answer is that adding the subprime acquisition fee to the sales price is a violation of the Truth in Lending Act and doing so for every subprime customer could potentially create a class-action lawsuit. Still a few dealers persisted in the practice, saying “I ain’t gonna pay juice for any subprime customer,” and I had to fire them as clients.
Thankfully, due to the efforts of many dealership advisers, I haven’t seen a deal where the subprime fee was added to the sales price in over a decade.
In today’s environment, I occasionally run into one of the following scenarios when reviewing deal files, and the unwanted answer remains the same:
Blank Signed Document
This scenario usually happens when a manager thinks he is helping a customer. It could also help a nefarious manager to kink a deal.
I’ve seen credit applications, statements of fact, credit union membership agreements, manufacturer purchase plan documents, powers of attorney, and voluntary protection product forms that are signed by the customer, but the form is devoid of any information.
The excuse is usually along the lines of trying to avoid inconveniencing the customer if the dealership had incorrectly completed the original document. “We don’t want to have the customer come back if the form needs to be resigned.”
While I generally believe the manager would not use the blank signed document to somehow kink the deal, I don’t want to leave that opportunity open. Some of these forms include a statement to the customer to not sign the form if it is blank.
My recommendation to dealers is a layered answer. First, in the policy manuals we write for dealers, we include a list of non-negotiables. This is a list of actions that could lead to termination. One of the actions in the non-negotiables is, “We will not have our customers sign any document that is blank.” Consider including expecting this of your managers.
The second recommendation is that electronic signing is an accepted process by consumers and finance sources. Asking a customer to electronically sign a document is usually an acceptable solution to avoid having the customer return to the dealership.
Backup Contract
A backup contract is just that. The F&I manager and the customer execute two valid retail installment sales contracts, or RISCs. In the past, the primary reason was that the dealer had finance sources who required either an RISC with an arbitration agreement or an RISC without an arbitration agreement. In the mind of the F&I manager, there was a contract that would be acceptable to any finance source, arbitration or not. This occurrence has lessened over the years as the credit approval process has sped up through the use of technology.
A different issue is now creeping into some dealers’ process - thanks again to technology. Any dedicated reader of my writings knows that I am a fan of digitizing the sales and F&I processes. E-contracting is a better process than printing an RISC and obtaining a wet-ink signature.
Some dealerships are experiencing sporadic temporary issues with the e-contracting process. For some reason, the e-contract will not process on the finance source’s end, requiring the manager to get the customer back into the dealership to recontract using a wet-ink signature. Some of the F&I managers believe it is more convenient for the customer (and themselves) to have the customer e-sign an RISC and wet-ink sign a paper RISC.
It is simply bad form to have two valid, executable RISCs on the same VIN to the same consumer. The practice simply must be outlawed by the dealership’s policy manual.
Continued Good Health, Good Luck, and Good Selling.
Gil Van Over is executive director of Automotive Compliance Education (ACE), founder and president of gvo3 & Associates, and author of “Automotive Compliance in a Digital World."
Originally posted on F&I and Showroom
More Industry
War Toll a Damper on Used Auto Prices
Cox Automotive found wholesale depreciation to be elevated in September amid high fuel prices and this year's unusual hurricane season.
Read More →
Bridge the Maintenance Gap
With many drivers missing recommended maintenance, service departments offering transparency and efficiency have a better chance of reaching financially strained consumers.
Read More →
California Store Has New Owner
The longtime dealership in the northern part of the state is known for robust fleet sales and has served the state capital for 115 years.
Read More →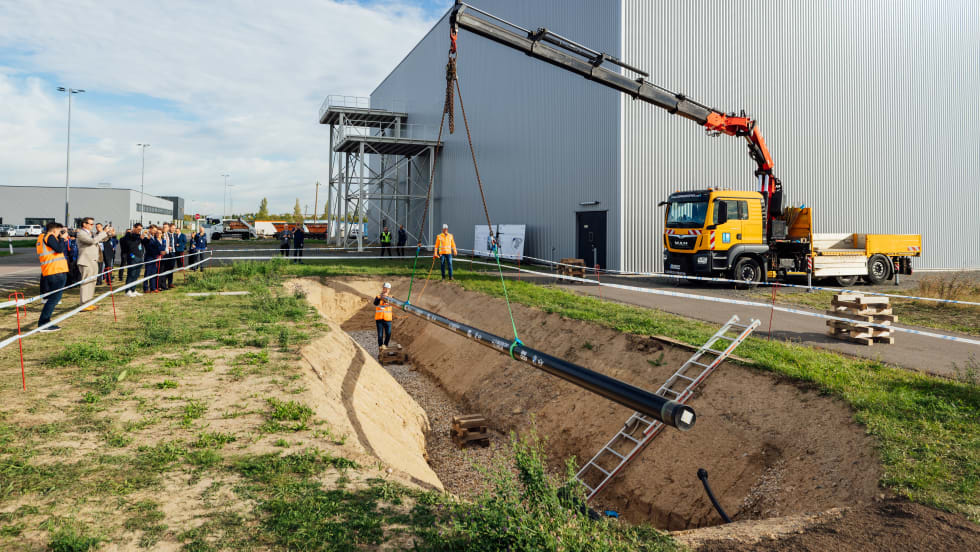
BMW Plant Pursues Cleaner Energy
BMW Group Plant Leipzig has utilized hydrogen to help power its production since 2013, but a new pipeline is planned to take it to another level.
Read More →
Auto Affordability Inches Up
The latest Cox Automotive and Moody’s Analytics index shows a slight increase in new-vehicle affordability despite high prices.
Read More →
Ohio Auto Group Under New Ownership
After 79 years with the Schluter family, Mansfield Auto Group has been acquired by Missouri-based Clement Auto Group.
Read More →
RV Group Expands Carolina Footprint
Blue Compass RV Columbia Northeast is the 13th RV dealership owned by Blue Compass in the Carolinas.
Read More →
Agent Acumen
An Agent Summit panel of people who’ve been supporting auto dealers for years gave both timely and timeless advice for those starting out or mulling the prospect.
Read More →
Missed Maintenance Creates Opportunity
As families get back on the road and into daily school routines, service drives have an opportunity to capture customers who are behind on recommended vehicle maintenance.
Read More →
Mitsubishi Unveils U.S. Plan
The automaker announced a strategy that includes an expanded lineup and dealership presence, along with more ‘rugged’ and electric models.
Read More →