

President Trump Orders Review of Dodd-Frank
WASHINGTON, D.C. — President Donald Trump took his first step toward making good on his promise to dismantle the Dodd-Frank Wall Street Reform and Consumer Protection Act, signing on Friday an executive order directing the secretary of the Treasury to review the 2010 financial oversight law. The order directs the Treasury secretary to consult with ... Read More »

WASHINGTON, D.C. — President Donald Trump took his first step toward making good on his promise to dismantle the Dodd-Frank Wall Street Reform and Consumer Protection Act, signing on Friday an executive order directing the secretary of the Treasury to review the 2010 financial oversight law.
The order directs the Treasury secretary to consult with members of regulatory agencies and the Dodd-Frank-created Financial Stability Oversight Council and report back to the president within 120 days (and periodically thereafter). The report, and all subsequent reports, will identify any laws and regulations that inhibit federal regulation of the U.S. financial system.
“Today we’re signing core principles for regulating the United States financial system,” Trump said after signing the order. “It doesn’t get much bigger than this, right?”
The core principles his order lays out include regulations that “empower Americans to make independent financial decisions”; prevent taxpayer-funded bailouts; foster economic growth; enable American companies to be competitive in domestic and foreign markets; advance American interests in international financial regulatory negotiations; and “restore public accountability within federal financial regulatory framework.”
“The Dodd-Frank Act is a disastrous policy that’s hindering our markets, reducing the availability of credit, and crippling our economy’s ability to grow and create jobs,” said White House Press Secretary Sean Spicer during a press briefing. “Perhaps worst of all, despite all of its overreaching, Dodd-Frank did not address the causes of the financial crisis, something we all know must be done.”
Enacted in response to the Great Recession, the Dodd-Frank Act created new regulations along with several new government enforcement agencies, including the Consumer Financial Protection Bureau (CFPB). While Trump’s order isn’t expected to have an immediate impact, it does set the stage for Trump to fulfill his campaign promise to repeal and replace the act. The likely replacement bill is the Financial CHOICE Act of 2016, which was introduced last year by Rep. Jeb Hensarling (R-Texas). It stands for “Creating Hope and Opportunity for Investors, Consumers and Entrepreneurs.”
“I’m very pleased that President Trump signed this executive action, which closely mirrors provisions that are found in the Financial CHOICE Act to end Wall Street bailouts, end ‘too big to fail,’ and end top-down regulations that make it harder for our economy to grow and for hardworking Americans to achieve financial independence,” said Hensarling. “Dodd-Frank failed to keep its promises, but President Trump is following through on his promise to the American people to dismantle Dodd-Frank. Republicans are eager to work with the president to end and replace the Dodd-Frank mistake …”
Repealing Dodd-Frank, however, doesn’t necessarily mean the CFPB will be eliminated, as it exists independent of the law that created it. However, regulatory insiders say passage of the Financial CHOICE Act could weaken the bureau. A federal appellate court also ruled the bureau’s single-director structure unconstitutional this past October, giving the president the power to remove Director Richard Cordray at will. The CFPB is appealing that decision.
Asked during Friday’s press briefing if the administration planned to keep Cordray, Spicer said he didn’t have an announcement on the bureau. “That’s an area that we need to work with Congress on,” he said.
More Industry
War Toll a Damper on Used Auto Prices
Cox Automotive found wholesale depreciation to be elevated in September amid high fuel prices and this year's unusual hurricane season.
Read More →
Bridge the Maintenance Gap
With many drivers missing recommended maintenance, service departments offering transparency and efficiency have a better chance of reaching financially strained consumers.
Read More →
California Store Has New Owner
The longtime dealership in the northern part of the state is known for robust fleet sales and has served the state capital for 115 years.
Read More →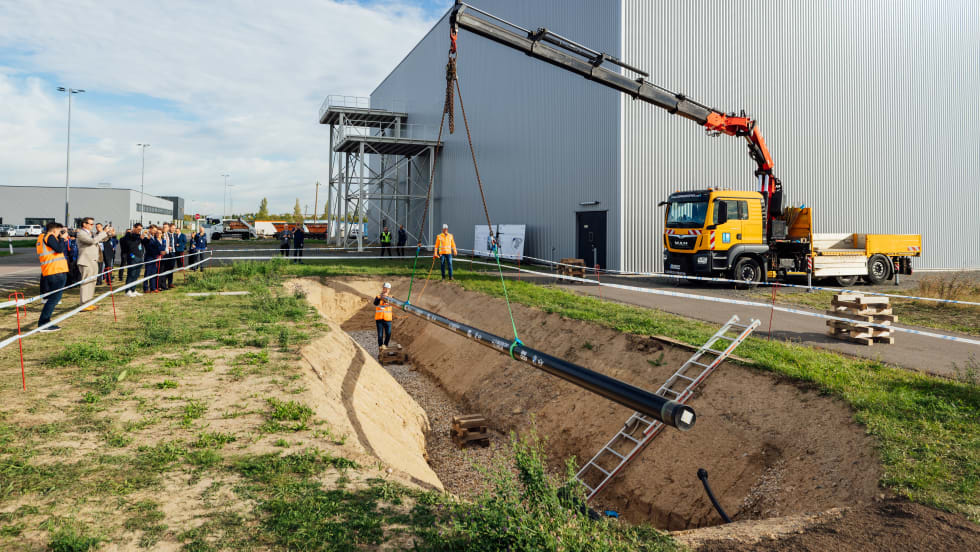
BMW Plant Pursues Cleaner Energy
BMW Group Plant Leipzig has utilized hydrogen to help power its production since 2013, but a new pipeline is planned to take it to another level.
Read More →
Auto Affordability Inches Up
The latest Cox Automotive and Moody’s Analytics index shows a slight increase in new-vehicle affordability despite high prices.
Read More →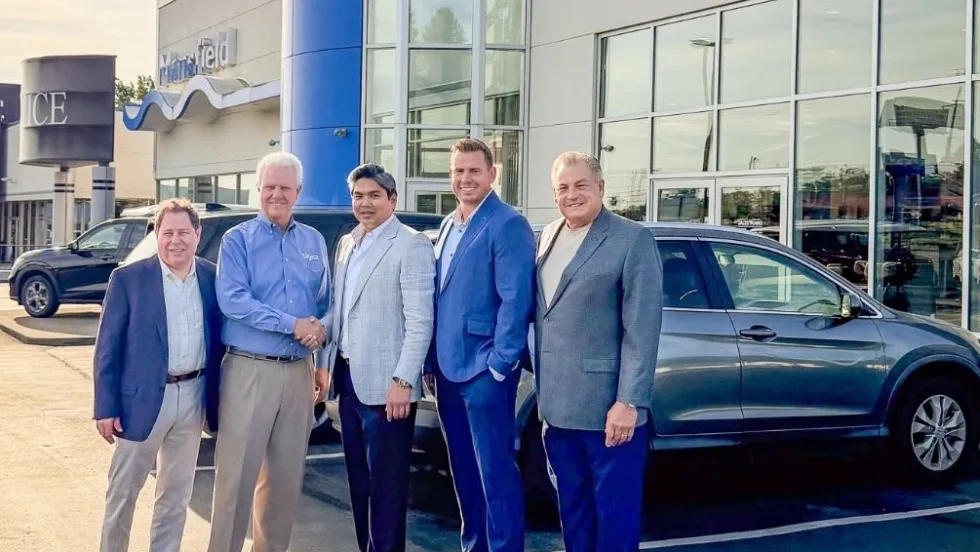
Ohio Auto Group Under New Ownership
After 79 years with the Schluter family, Mansfield Auto Group has been acquired by Missouri-based Clement Auto Group.
Read More →
RV Group Expands Carolina Footprint
Blue Compass RV Columbia Northeast is the 13th RV dealership owned by Blue Compass in the Carolinas.
Read More →
Agent Acumen
An Agent Summit panel of people who’ve been supporting auto dealers for years gave both timely and timeless advice for those starting out or mulling the prospect.
Read More →
Missed Maintenance Creates Opportunity
As families get back on the road and into daily school routines, service drives have an opportunity to capture customers who are behind on recommended vehicle maintenance.
Read More →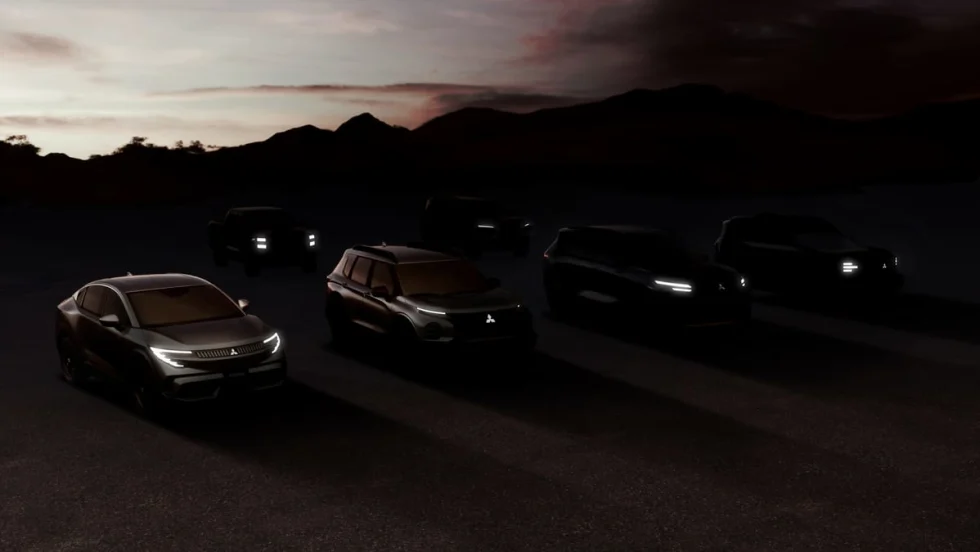
Mitsubishi Unveils U.S. Plan
The automaker announced a strategy that includes an expanded lineup and dealership presence, along with more ‘rugged’ and electric models.
Read More →