

Architects of GM's IPO Sought to Limit Windfall for Wall Street

Want to underwrite one of the largest initial public offerings in history? Chop your usual fee by three-fourths and commit to limiting Wall Street’s windfall.
That was the deal David Miller and Tim Massad, the unheralded government architects behind the General Motors Co. stock offering, gave investment banks interested in handling the deal. When the two U.S. Treasury officials made their expectations clear, “we could kind of hear their jaws drop over the phone,” said Massad, Bloomberg Businessweek reported.
Massad, acting assistant secretary for financial stability, and Miller, chief investment officer for the Troubled Asset Relief Program, were President Barack Obama’s dealmakers on the Nov. 17 sale of GM stock, along with two Obama aides -manufacturing czar Ron Bloom and economic adviser Brian Deese.
The IPO, led by JPMorgan Chase & Co. and Morgan Stanley, was a nail-biter for Massad and Miller, who also manage the government’s bank and insurance company investments.
“You want the deal to go well” without looking overly optimistic in pricing the shares, Miller said. “At the same time, we don’t want it to go up way too much” because that would mean taxpayers left money on the table on the first day of trading.
GM’s shares, initially priced at $33, rose 3.6 percent on Nov. 18, the first day of trading - exactly the “sweet spot” Miller and Massad wanted. Of the nearly $20 billion raised, almost $12 billion went to the U.S.
Treasury officials “passed with flying colors,” said Jay Ritter, a finance professor at the University of Florida in Gainesville who studies IPOs.
No Break Even
Taxpayers, however, haven’t broken even on GM. The government needed to sell its entire stake for about $44 a share for that to happen. The U.S. would need to sell its remaining 37 percent ownership of GM at $53 a share for taxpayers to be made whole.
Miller and Massad said they aren’t waiting for the stock to reach that level.
“We’re not a private equity fund,” Massad said. “We believe that promoting financial stability means we should exit as soon as we can.”
Of the $50 billion the government gave GM in 2008 and early 2009 when the auto industry was near collapse, Treasury says it will recover $9.5 billion through interest, loan repayments, and preferred stock dividends.
Ultimately, the government may lose $5 billion to $7 billion of the $85 billion auto industry rescue effort, Steven Rattner, former head of the President’s auto task force, said in a Nov. 17 Bloomberg Radio interview.
Banking Fees
Investment banking fees were one of the trickiest parts of the deal, said Herb Allison, the former Fannie Mae and Merrill Lynch executive who led Treasury’s financial stability office from June 2009 through September 2010.
If the government were too soft on the investment firms, Wall Street would profit at taxpayer expense. If too strict, the best firms might walk away. “That was a difficult decision,” Allison said of Treasury’s demand for a 0.75 percent fee. “I think it proved to be the right one.”
Massad, 54, is a former corporate lawyer at Cravath, Swaine & Moore who has worked on hundreds of IPOs, although this is his first one as the client. He earned undergraduate and law degrees from Harvard.
Miller, 34, worked on deals in Goldman Sachs Group’s special situations unit, laying the groundwork for his job managing TARP’s complex mix of preferred shares, common stock, warrants, guarantees and dividend agreements. Before going to Harvard Business School he studied economics at Dartmouth, where he also minored in film studies.
Auto Stake
The pair’s labors aren’t over yet. They still need to manage the rest of the government’s auto stake, along with its holdings in American International Group Inc., Citigroup, and hundreds of smaller institutions.
“We have responsibility for almost $200 billion of assets and only one of those, which is very important, is General Motors,” Miller said. “While it would have been nice to spend the day watching and feeling good about it, there was other business to attend to.”
More Industry
Auto Affordability Inches Up
The latest Cox Automotive and Moody’s Analytics index shows a slight increase in new-vehicle affordability despite high prices.
Read More →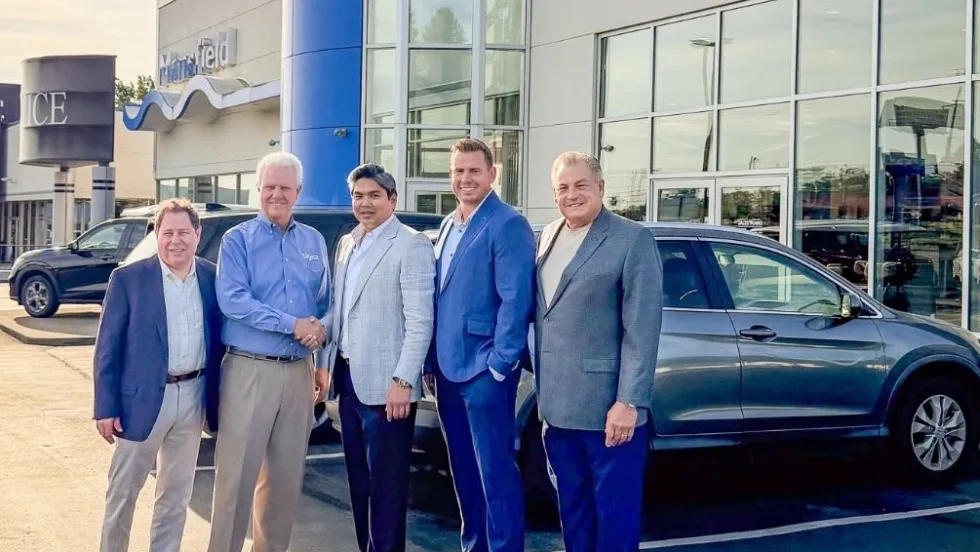
Ohio Auto Group Under New Ownership
After 79 years with the Schluter family, Mansfield Auto Group has been acquired by Missouri-based Clement Auto Group.
Read More →
RV Group Expands Carolina Footprint
Blue Compass RV Columbia Northeast is the 13th RV dealership owned by Blue Compass in the Carolinas.
Read More →
Agent Acumen
An Agent Summit panel of people who’ve been supporting auto dealers for years gave both timely and timeless advice for those starting out or mulling the prospect.
Read More →
Missed Maintenance Creates Opportunity
As families get back on the road and into daily school routines, service drives have an opportunity to capture customers who are behind on recommended vehicle maintenance.
Read More →
Mitsubishi Unveils U.S. Plan
The automaker announced a strategy that includes an expanded lineup and dealership presence, along with more ‘rugged’ and electric models.
Read More →
Selling to Grow
The question of whether you should sell your agency and if so, when, is up to you. But it’s a question worth asking to ensure you keep the business on the right path for yourself, employees and clients.
Read More →
Recalled Vehicles Hit 5-Year High
Though the number of events has fallen so far this year, impacted units are up significantly. Meanwhile, regulators consider consumer notification changes.
Read More →
Auto Group Acquires Top-Performing Rooftop
Car Pros sold its Kia Huntington Beach location to Sutherlin Automotive Group, marking the buyer’s third location in Southern California.
Read More →
China as Pacesetter
Automotive leaders huddled on where North America stands in the global picture and how it can strengthen its position against the Asian juggernaut’s surging industry.
Read More →