

Captives are Monitoring Disparate Impact
There are at least three reasons your dealers need data when confronted with allegations of disparate impact.
There are at least three reasons your dealers need data when confronted with allegations of disparate impact.
IMAGE: Getty Images
“Gil, my sales rep from (insert name of captive) just left my office and …”.
I’ve received three phone calls from dealer principals over the last month that started the same way. Three different captives, same message.
The captive had completed an analysis of the dealer’s originations during the last quarter and are alleging that the dealer has a higher than acceptable spread between buy rate and sell rate for a protected class of consumers. One dealer was told that Hispanics paid 18 basis points higher in dealer reserve than the control group. Another dealer had a 21 basis points differential for Black consumers versus the control group.
These captives have not taken the Nissan and Infiniti approach. Yet, as you may know, Nissan and Infiniti dealers recently elected to either a flat rate compensation structure or to adapt the NADA Fair Lending Program for retail transactions through the captive.
This monitoring is likely due to the Consumer Financial Protection Bureau (CFPB) signaling it will be looking at the finance sources portfolio for instances of disparate impact. As a refresher, disparate impact occurs when a protected class under the Equal Credit Opportunity Act is unintentionally discriminated against. The dealer does not intend to discriminate, it is just that the result of the originations delivers a contrary result.
Since our finance sources do not have definitive access to consumers’ demographic data, it must use a proxy approach to conduct its analysis. The CFPB uses the Bayesian Improved Surname Geocoding (BISG) as a proxy and the finance sources who are regulated by this agency use the same methodology to monitor a dealer’s portfolio. This approach uses census data and relies on surnames (from the 2000 Census) and geographic information (from the 2010 Census).
For example, you may know a Caucasian woman who married a Hispanic and now has a Hispanic surname. She should be part of the control group yet would likely be counted as a part of the protected class group based on her married surname.
One of the dealers voluntarily monitors every retail transaction using the NADA Fair Lending Program. It set a standard mark up of 1.00%. Every retail deal has a Dealer Participation Certification Form which documents the legitimate business reason for coming off the standard mark up. The sales rep was not impressed.
The sales rep did share, off the record, that the problem would probably go away if the dealer were to close a couple of deals to white guys at a higher rate!
So, the sales rep is recommending that the dealer engage in intentional discrimination to cure a potentially flawed finding of unintentional discrimination. Classic.
Further, this sales rep was not permitted to share any of the data to support the captive’s claim. The dealer rightfully asked for the list of deals that were identified as Hispanic. He reminded the sales rep of the NADA Fair Lending Policy and his voluntary use of the program to be able to defend against claims of disparate impact. The sales rep wouldn’t budge.
There are at least three reasons you need the data when confronted with allegations of disparate impact.
First, you need the names of the deals to reverse engineer the deals. If you are not completing the Dealer Participation Certification form on every retail deal, you will need to do so when you start reverse engineering. Look at all the deals that were contracted at less than your standard markup and determine the business reason for coming off the standard markup. Hopefully it will support a lack of discriminatory pricing.
Another reason for having the list of deals is to review the customer’s identity documents to verify (to the best of your ability) that the consumer is truly part of the protected class.
Finally, knowing the sample size and number of deals that are included to reach the captive’s conclusion is important. For example, if the captive looked at 100 deals during the review period and there were three deals it identified as the protected class group, a legitimate argument is that the sample size was too small to deliver a valid result.
Buckle up and help your dealer-partners be ready for their visit.
Continued Good Health, Good Luck, and Good Selling.
Gil Van Over is the Executive Director of Automotive Compliance Education (ACE), the Founder and President of gvo3 & Associates, and the author of Automotive Compliance in a Digital World.
More Industry
California Store Has New Owner
The longtime dealership in the northern part of the state is known for robust fleet sales and has served the state capital for 115 years.
Read More →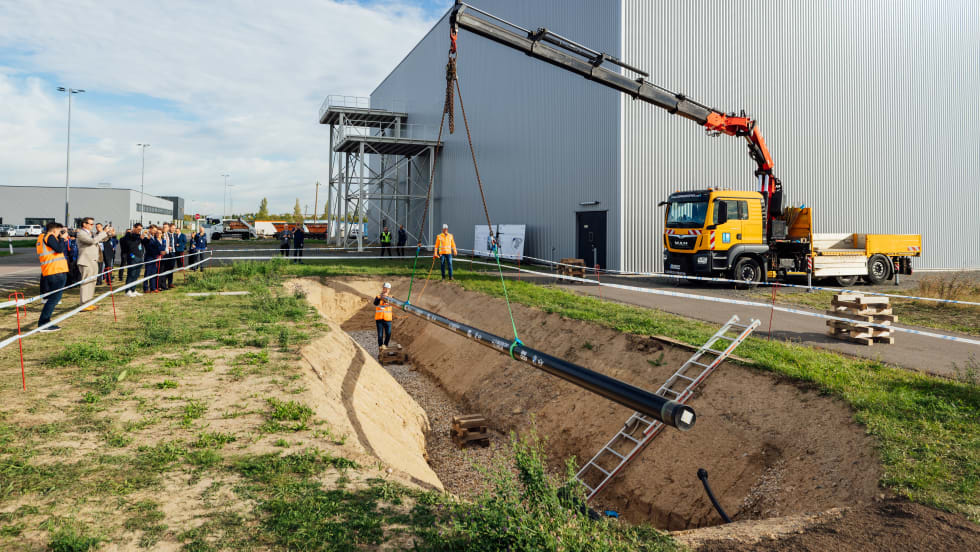
BMW Plant Pursues Cleaner Energy
BMW Group Plant Leipzig has utilized hydrogen to help power its production since 2013, but a new pipeline is planned to take it to another level.
Read More →
Auto Affordability Inches Up
The latest Cox Automotive and Moody’s Analytics index shows a slight increase in new-vehicle affordability despite high prices.
Read More →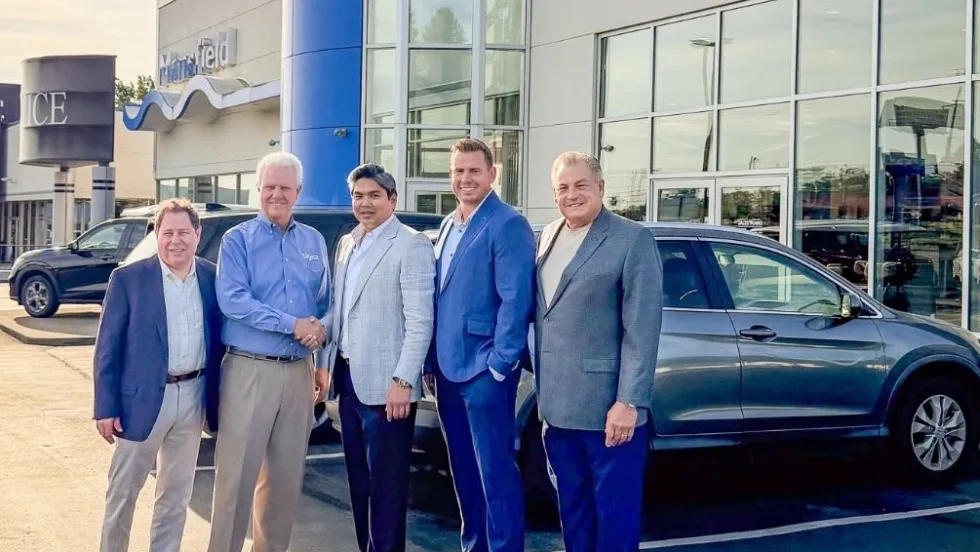
Ohio Auto Group Under New Ownership
After 79 years with the Schluter family, Mansfield Auto Group has been acquired by Missouri-based Clement Auto Group.
Read More →
RV Group Expands Carolina Footprint
Blue Compass RV Columbia Northeast is the 13th RV dealership owned by Blue Compass in the Carolinas.
Read More →
Agent Acumen
An Agent Summit panel of people who’ve been supporting auto dealers for years gave both timely and timeless advice for those starting out or mulling the prospect.
Read More →
Missed Maintenance Creates Opportunity
As families get back on the road and into daily school routines, service drives have an opportunity to capture customers who are behind on recommended vehicle maintenance.
Read More →
Mitsubishi Unveils U.S. Plan
The automaker announced a strategy that includes an expanded lineup and dealership presence, along with more ‘rugged’ and electric models.
Read More →
Selling to Grow
The question of whether you should sell your agency and if so, when, is up to you. But it’s a question worth asking to ensure you keep the business on the right path for yourself, employees and clients.
Read More →
Recalled Vehicles Hit 5-Year High
Though the number of events has fallen so far this year, impacted units are up significantly. Meanwhile, regulators consider consumer notification changes.
Read More →