

Put It in Writing

When people enter into a business partnership, they do so with a lot of optimism and hope that the business will expand and that they’ll both benefit financially. The fact is that even if they do make money, it’s usually a long process that resembles a roller coaster ride. During this process, memories of what constituted the original partnership can and do change. Here are some simple tips to help ensure that a business partnership gets off to a good start and can stand the test of time:
1. Put The Terms of The Partnership in Writing. This should be done as soon as two people agree to become partners and start a business. You cannot rely on memory because everybody remembers things differently and tends to lean toward whatever yields the best result for them.
2. Be Specific About The Terms of The Contract. Include details such as salary, partner draws, individual and partner responsibilities, and even how to deal with disagreements.
3. Review The Contract on a Regular Basis. Doing this enables you to make appropriate changes that reflect growth and other changes that occur within the business.
4. Establish What The Buyout Terms Are And Who Has The Right to Initiate One. If an issue comes up to which a resolution can’t be found, terms of a buyout or change in ownership are important to have in place so that emotion can be taken out of the equation.
Do yourself a favor and follow these four simple steps if you decide to enter into a partnership. Doing so will prevent one partner or a majority partner from having the ability to change the terms on the fly to suit his or her needs.
This article was written by Brad Walters and published in Bloomberg Businessweek magazine.
More Training
Major Shifts in F&I Training
General agents must help F&I managers rise to the occasion of the modern consumer, who has very different expectations in order to relax into trust.
Read More →
Be a Compliance Hero
Agents can steer their dealer clients toward proper advertising practices, including regular audits, to help keep them on the straight and narrow in a period of elevated regulation.
Read More →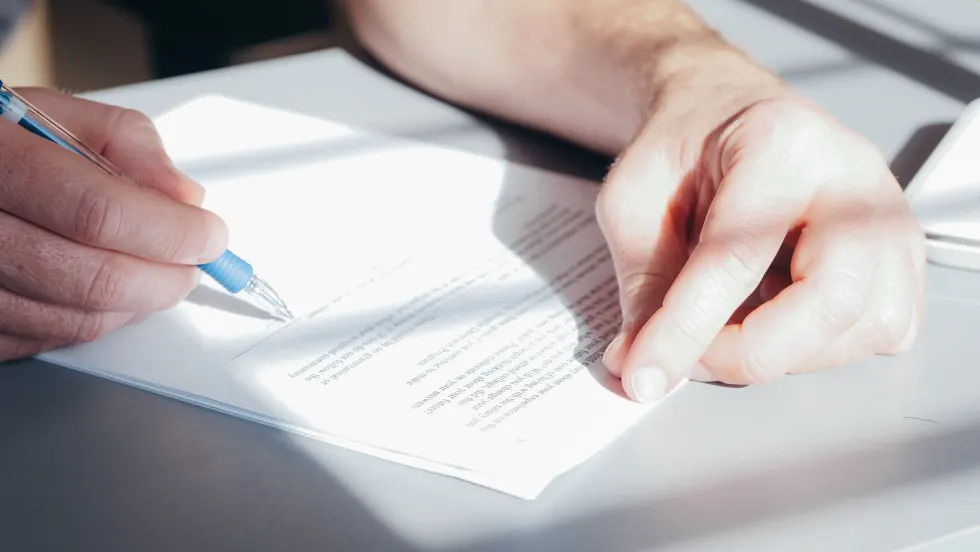
Leasing Is Picking Up. What About Disclosures?
Agents and dealers must ensure proper documentation of lease costs and funding and end the practice of wedging lease orders into buyer’s orders — or ignoring them.
Read More →
Manage Change, or It Will Manage You
Two retail tales from the pandemic paint a stark contrast in the wise approach and the defensive move that will undercut success rather than build on it.
Read More →
Train the Mind, Grow the Department
Agents who want to create real value must do more than bring coverage options. They must help dealers build stronger thinking, better habits and better results.
Read More →
Headlines Can Be Deceiving
Warning letters the FTC sent to dealers suspected of deceptive pricing have retailers and the agents who counsel them on edge. Read past the headlines to get and stay compliant.
Read More →
Service Drive Satisfaction Up
Auto dealerships have a ways to go, though, on many basic points, along with some new consumer expectations that would boost their competitiveness if fulfilled.
Read More →
Agents Bring the Message and the Focus
The most predictable profit in today's unpredictable automotive retail market is a dealership’s finance-and-insurance department.
Read More →
Policy Responses to Data Breaches
The recent 700Credit cyberattack is a wake-up call for agents and dealers. Review disclosures and tighten vendor oversight to maintain compliance and preserve customer trust.
Read More →
How Agents Help Dealers Avoid Bust-Out Scams
Update your F&I training program to include the three warning signs of a bust-out, or a nefarious, two-pronged form of bank fraud that leaves dealers and finance sources holding the bag.
Read More →